Loans
Is Upstart a Good Option for a Personal Loan?
Discover the main features of Upstart personal loans and what to consider before applying
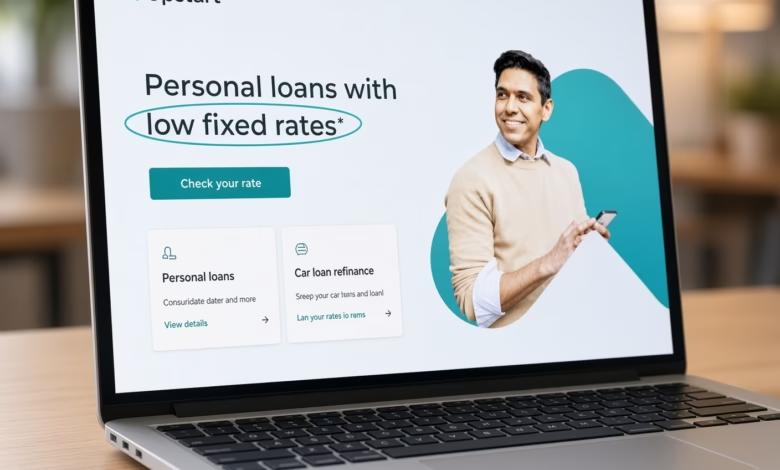
Navigating the financial landscape when you need extra cash can feel overwhelming. Traditional banks often rely strictly on rigid credit scores, leaving many credit-builders, young professionals, and everyday consumers out in the cold. If you have ever been turned down by a traditional lender despite having a steady job and reliable income, you know how frustrating the lending system can be.
Enter online lending platforms that utilize modern technology to evaluate borrowers. Among them, Upstart has carved out a massive presence in the personal loan industry. But is Upstart a good option for a personal loan? To answer this question accurately, we need to dive deep into how the platform works, its core requirements, its advantages, its drawbacks, and how it compares to other financial products on the market.
Understanding How Upstart Personal Loans Work
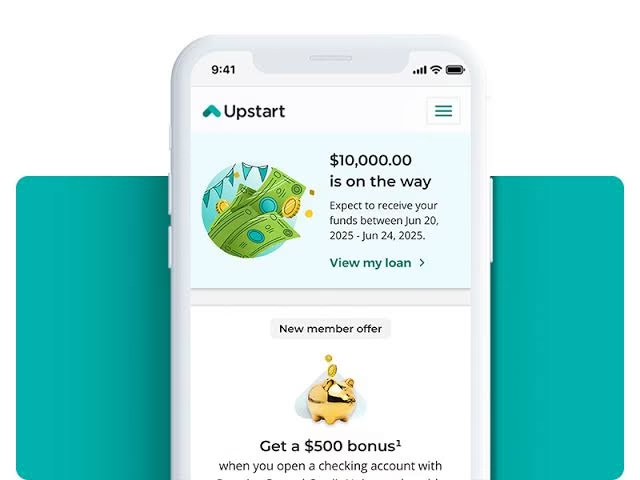
Unlike traditional banks that typically look only at a standard three-digit credit score and debt-to-income ratio, Upstart takes a broader view. Founded by former Google executives, the company pioneered an artificial intelligence (AI) and machine learning underwriting platform.
When you submit an application, Upstart evaluates thousands of variables beyond your traditional credit history. These alternative data points often include:
-
Your level of education and degree earned
-
Your area of study or academic performance
-
Your job history, current employment, and employer stability
-
Your living situation and residence history
By incorporating these factors, Upstart aims to determine your true earning potential rather than just looking at past financial mistakes. This model allows the platform to approve loans for applicants who might otherwise be rejected by conservative financial institutions.
Key Features and Loan Terms Offered by Upstart
Before committing to any financial product, it is vital to understand the basic parameters of what is being offered. Upstart provides unsecured personal loans that can be used for various purposes, such as debt consolidation, home improvements, medical expenses, or major life events.
-
Loan Amounts: Borrowers can generally apply for amounts ranging from $1,000 to $75,000, though minimum limits can vary depending on your state of residence.
-
Repayment Terms: Upstart keeps things simple by offering only two repayment term options: 3-year (36 months) or 5-year (60 months) fixed-rate terms.
-
Interest Rates: Annual Percentage Rates (APRs) typically range from competitive starting rates up to a maximum of 35.99%.
-
Funding Speed: One of Upstart’s biggest selling points is speed. If your loan is approved and finalized, funds are often deposited into your checking account as soon as the next business day.
The Pros: Why Borrowers Choose Upstart
Upstart has gained significant popularity for several distinct reasons. If you fit into a specific borrower profile, the platform can be an exceptional tool.
Accessible Qualification Criteria
The most significant benefit of using Upstart is its inclusive approval model. While traditional lenders might shut their doors to anyone with a thin credit file or a past financial hiccup, Upstart looks at your education and employment history to paint a complete picture. This makes it a popular destination for younger consumers or those actively working to rebuild their credit standing.
Soft Credit Check Prequalification
Nobody wants their credit score to drop just for shopping around. Upstart allows prospective borrowers to check their potential rates using a soft credit inquiry. This means you can see what terms you might qualify for without harming your credit score. A hard credit pull only occurs if you officially accept the loan offer.
Rapid Funding Turnaround Time
When you face an urgent financial obligation, waiting weeks for bank approval is not an option. Upstart features a streamlined, fully digital application process. Many applicants receive an instant decision online, and once accepted, funds move quickly into your bank account.
The Cons: Potential Drawbacks and Fees to Watch Out For
While Upstart offers clear perks, it is not a one-size-fits-all solution. Smart borrowers always weigh the disadvantages before signing a promissory note.
High Origination Fees
Upstart charges a one-time origination fee that can range up to 12% of the total loan amount. This fee is typically deducted directly from your loan proceeds before the funds are disbursed, meaning you will receive slightly less cash in hand than the total amount you borrowed while still being responsible for paying back the full balance.
Potentially High APRs for Lower Credit Tiers
While well-qualified borrowers can secure low interest rates, individuals with lower credit scores or limited credit histories may receive rates on the higher end of the spectrum. A high-interest loan combined with a steep origination fee can make borrowing quite expensive.
Limited Repayment Flexibility
Upstart strictly offers 3-year or 5-year loan terms. If you want a shorter term—such as 12 or 24 months—or a longer term to lower your monthly payments, you will not find those options here.
Absence of Autopay Discounts
Many competing online lenders and traditional banks offer a small interest rate discount (usually around 0.25%) if you enroll in automatic monthly payments. Upstart does not provide rate discounts for autopay setups.
Who is an Upstart Personal Loan Best For?
Knowing where you stand financially helps determine if Upstart aligns with your goals. Upstart tends to be a strong option for:
-
Consumers with fair or limited credit: If your credit score is on the lower side or you simply do not have a long history of borrowing, Upstart’s alternative data evaluation can give you a fair shot at approval.
-
Borrowers needing fast cash: When speed is a top priority, the rapid digital verification and next-day funding windows are hard to beat.
-
People looking for smaller loan amounts: Because loans start at $1,000, it caters well to those who do not need massive sums of money.
Conversely, if you possess excellent credit and a long, spotless financial history, you may qualify for lower interest rates and zero origination fees through other prime lending institutions or credit unions.
Alternatives to Consider in the Personal Loan Market
Before finalizing your decision, it is always wise to shop around and compare multiple lenders. The personal loan marketplace features several prominent alternatives:
-
Traditional Banks and Credit Unions: Local credit unions often provide lower interest rates and fewer hidden fees, though their membership requirements and approval processes can be more restrictive.
-
Competitor Online Lenders: Companies like SoFi, LightStream, and Upgrade offer alternative lending products with different fee structures, varying term lengths, and potential autopay incentives.
Comparing offers side by side ensures you secure the lowest possible cost of borrowing for your unique situation.
Step-by-Step Guide: How to Apply for an Upstart Loan
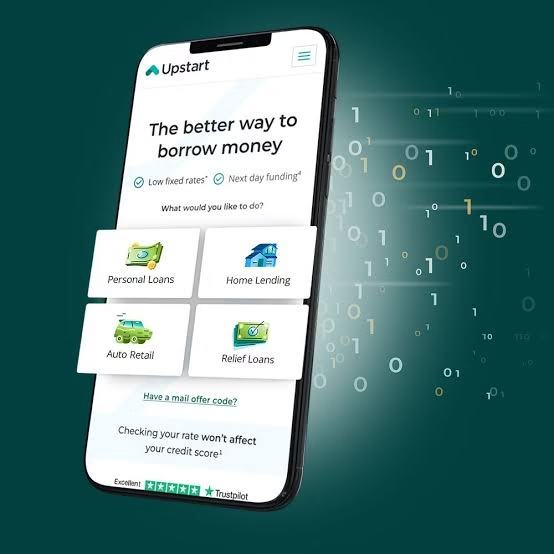
If you decide that Upstart matches your financial needs, the application process is straightforward and entirely online.
-
Check Your Rate: Visit the official website and navigate to the rate-checking tool. Enter basic personal, employment, and financial details. Remember, this triggers a soft credit check that will not hurt your credit score.
-
Review Your Options: If you prequalify, Upstart will present you with specific loan amounts, interest rates, and monthly payment options for both 3-year and 5-year terms.
-
Select Your Terms: Choose the loan amount and repayment schedule that comfortably fits into your monthly budget.
-
Complete Verification: Provide any requested documentation, such as proof of income or identity verification, to finalize your application.
-
Sign and Receive Funds: Read through the final loan disclosures carefully, sign the promissory note electronically, and look out for your funds as soon as the next business day.
Is Upstart Worth It?
Ultimately, whether Upstart is a good option for a personal loan depends entirely on your personal financial profile and borrowing objectives. For individuals with fair credit or limited borrowing histories who struggle to get approved through conventional banking channels, Upstart offers a modern, accessible pathway to funding.
However, because the platform can charge high origination fees and upper-tier interest rates, applicants with strong credit should carefully compare competing offers to ensure they are getting the most cost-effective deal possible. Always evaluate your monthly budget, calculate the total cost of the loan including all fees, and borrow responsibly to keep your financial future secure.