How to Recognize Fake Check Scams
Understand how counterfeit check scams work and why a deposited check may later be rejected by your bank
Understanding Fake Check Scams and How the Fraud Works
At its core, a fake check scam relies on a fundamental misunderstanding of how banks process deposited checks. When you deposit a check into your bank account, federal law in many regions requires the bank to make those funds available to you quickly—often within one to two business days. However, making funds available is not the same thing as the check actually clearing.
Clearing a check involves a complex background communication process between the bank where the check was deposited and the bank upon which the check was drawn. Verifying that the check is authentic, that the account exists, and that sufficient funds are present can take several days or even weeks. During this window, the deposited funds appear in your available account balance, creating a dangerous false sense of security.
Scammers exploit this delay by asking you to deposit a check and immediately send a portion of those funds back to them or to a third party. Days or weeks later, when the bank finally discovers that the check is counterfeit, stolen, or fraudulent, the transaction is reversed. Because you are legally responsible for every document you deposit into your account, your bank will deduct the full check amount from your funds. If you have already wired or transferred money to the scammer, that money is gone forever, leaving you with a negative bank balance and serious financial consequences.
The Most Common Fake Check Scam Variations to Watch Out For
Fraudsters use a variety of convincing setups to lure victims into accepting fraudulent checks. Recognizing these scenarios is key to identifying fraud before it ruins your financial standing. Here are the most prevalent variations active today:
1. Mystery Shopping and Work-from-Home Job Offers
In this variation, you apply for a remote job, virtual assistant position, or mystery shopper role online. Shortly after being hired, the employer sends you a substantial check. They instruct you to deposit the funds and use a large portion of the money to purchase office equipment, gift cards, testing supplies, or software from a specific preferred vendor. Naturally, the vendor is the scammer in disguise. Once you send the money, the original check bounces, and the job offer evaporates.
2. Overpayment Scams on Online Marketplaces
If you sell items online via classified sites, social media platforms, or personal web pages, you are a primary target for overpayment schemes. A buyer contacts you expressing strong interest in your item and sends a check for payment. However, the check arrives for significantly more than the agreed-upon selling price. The buyer quickly follows up with a plausible explanation—claiming it was an administrative error by their accounting department or an extra amount intended to cover shipping fees. They politely request that you deposit the full check and transfer the excess money back to them. Shortly after you refund the difference, the check is exposed as fraudulent.
3. Lottery, Sweepstakes, and Foreign Grant Winnings
You receive an official-looking letter or email announcing that you have won a major lottery, sweepstakes, or educational grant. Attached to the notice is a realistic check representing an advance on your total prize winnings. The instructions direct you to deposit the check immediately and wire back a percentage to cover administrative taxes, processing fees, or legal clearance costs. In reality, legitimate sweepstakes and lotteries never require winners to pay money or wire funds upfront to claim a legitimate prize.
4. Caregiver, Babysitter, and Domestic Service Scams
Individuals offering personal services, such as tutors, pet sitters, house cleaners, and senior caregivers, are frequent targets. A prospective client reaches out online offering employment and agrees to pay in advance. They send a check that exceeds the agreed payment and instruct the provider to keep their fee and wire the remainder to a landlord, moving company, or medical supply vendor on their behalf. Once the money is sent, the client vanishes and the check bounces.
5. Rental Property and Roommate Deposit Schemes
Landlords and people advertising open rooms for rent often receive inquiries from out-of-town applicants. The prospective tenant sends a check covering the first month’s rent along with the security deposit. Shortly after sending the payment, the fake tenant claims a sudden family emergency forces them to cancel their move. They ask the property owner to refund a portion of the deposit via electronic transfer. After the landlord sends the funds, the original rental check is rejected by the bank.
Red Flags: How to Instantly Spot a Fake Check
While counterfeit checks have become sophisticated due to modern high-resolution printing techniques, careful inspection reveals critical warning signs. If you encounter any of the following physical or contextual red flags, exercise extreme caution before proceeding with a deposit:
* Payment Exceeds the Agreed Amount: Any transaction where someone intentionally pays you more than requested and asks for money back is almost guaranteed to be a fraudulent scheme.
* Demands for Fast Money Transfers: Scammers push for immediate action using wire transfers, peer-to-peer payment apps, cryptocurrency, or gift card codes. These non-refundable transfer methods prevent you from recovering your funds once the fraud is uncovered.
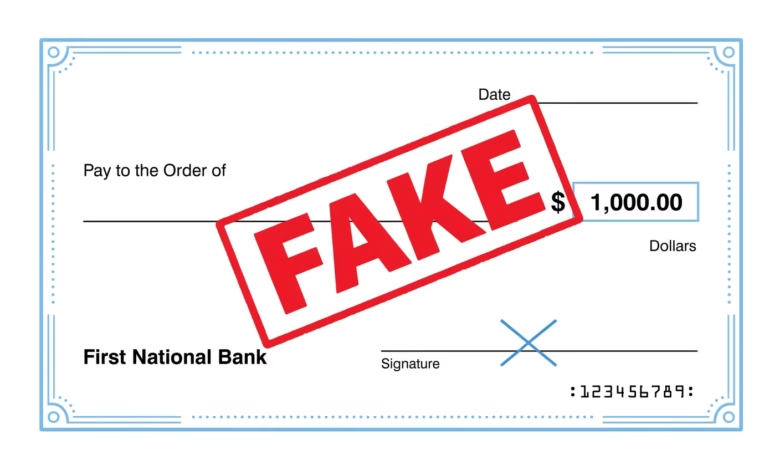
* Mismatched Financial Information: Inspect the document carefully. The name and address of the issuing company printed on the check should perfectly match the bank details. Look out for different state addresses, spelling errors, or unusual logos.
* Lack of Physical Security Features: Authentic checks issued by reputable financial institutions feature subtle safety elements, such as microprinting on the signature line, watermarks, and clear routing numbers printed in magnetic ink. Fake checks often feel flimsy, lack smooth perforations along the edges, or show blurry text.
* Unsolicited Checks by Mail: Receiving a check in the mail from an unknown individual or organization for a contest you never entered or a job you never applied for is an immediate warning sign.
The Legal and Financial Consequences of Depositing Fake Checks
A common misconception among scam victims is that the bank bears responsibility for accepting a bad check. Legally, the account holder who deposits the check is fully accountable for the validity of all items deposited into their account. Understanding the consequences helps highlight the importance of vigilance:
Total Financial Liability
When a deposited check bounces, your bank removes the full amount of that check from your account. If you spent or transferred any part of those funds, your account balance will fall into a negative status. You must repay the bank every dollar out of your own pocket.
Returned Item Fees and Account Penalty Charges
Banks typically charge a returned deposit fee when an item fails to clear. Furthermore, if the reversal causes your account to drop below zero, you may face multiple overdraft fees for subsequent transactions.
Account Closure and Loss of Banking Privileges
Financial institutions closely monitor accounts involved in fraudulent activity. Depositing fake checks—even unknowingly—marks your account as high risk. The bank reserves the right to freeze your remaining funds, close your checking account, and report your account history to consumer reporting agencies like ChexSystems. This record can make opening a new bank account anywhere else extremely difficult for up to five years.
Potential Criminal Investigation
While banks usually distinguish between innocent victims and deliberate fraudsters, repeatedly depositing altered or counterfeit checks can raise legal concerns. You could face questioning by law enforcement agencies investigating check fraud, adding emotional stress to an already difficult financial situation.
Step-by-Step Action Plan: What to Do If You Receive a Suspicious Check
If you receive a check that raises suspicions or accompanies an unusual request, taking proactive, methodical steps can save you from catastrophic financial losses. Follow this step-by-step action plan to safeguard your accounts:
1. Do Not Deposit the Check
The single most effective protection is refusing to deposit or cash the document. Holding onto the physical check keeps the fraud outside your banking environment completely, preventing any potential fees or account freezes.
2. Verify the Check Independently
Never rely on phone numbers, website addresses, or contact information printed directly on the check itself, as these are often routed to the scammer’s co-conspirators. Instead, look up the issuing bank’s customer service number independently through an official website or directory. Call the bank directly and ask their fraud department to verify the check number, account status, and dollar amount.
3. Never Send Money Back to the Payee
Regardless of how compelling, urgent, or emotional the sender’s explanation sounds, never send money back via wire transfers, prepaid debit cards, gift cards, or instant payment apps. Legitimate businesses and buyers will handle payment corrections through transparent, verifiable banking channels.
4. Wait for Full Clearance Before Spending
If you have already deposited a check that you later come to suspect, do not touch those funds. Remember that available funds do not mean cleared funds. Ask your bank representative specifically when the check will fully clear through the issuing institution, and wait until that clearance period completely concludes before utilizing any portion of the money.
How to Report Fake Check Scams to Protect Others
Taking action against scammers helps consumer protection organizations track fraudulent networks and prevent future attacks. If you encounter a fake check scheme, file detailed reports with the following authorities:
* Your Local Police Department: Filing a official police report creates a legal paper trail, which can be helpful if your bank questions your involvement or if identity theft is suspected.
* The Federal Trade Commission (FTC): Submit a complaint through the official FTC consumer reporting portal to help government regulators monitor emerging scam trends and take enforcement actions against fraud rings.
* The U.S. Postal Inspection Service: If the fraudulent check arrived at your home via mail, report the incident to postal inspectors, as mail fraud is a serious federal offense.
* The Internet Crime Complaint Center (IC3): For scams originating from online interactions, email communication, or marketplace platforms, lodge a report with the FBI’s IC3 portal.
* The Issuing Financial Institution: Inform the fraud division of the bank whose name appears on the face of the counterfeit check so they can alert the account holder whose information may have been stolen.
Essential Financial Habits to Keep Your Money Safe permanently
Building long-term immunity against financial scams requires adopting safe, disciplined banking habits. By maintaining a cautious mindset toward unexpected financial offers, you create a powerful barrier against fraudsters.
Always remember that legitimate employers, buyers, and organizations operate with complete financial transparency. They will never ask a candidate or seller to handle third-party payments or return excess funds via untraceable methods. Treat any unexpected financial gain that comes with conditions as a potential hazard. By protecting your personal information, questioning unusual transactions, and verifying payments directly with trusted institutions, you can navigate your personal finances with complete safety and peace of mind.