Loans
How Does LightStream Lending Work?
See how LightStream loans work and explore the main features, requirements, and costs for borrowers
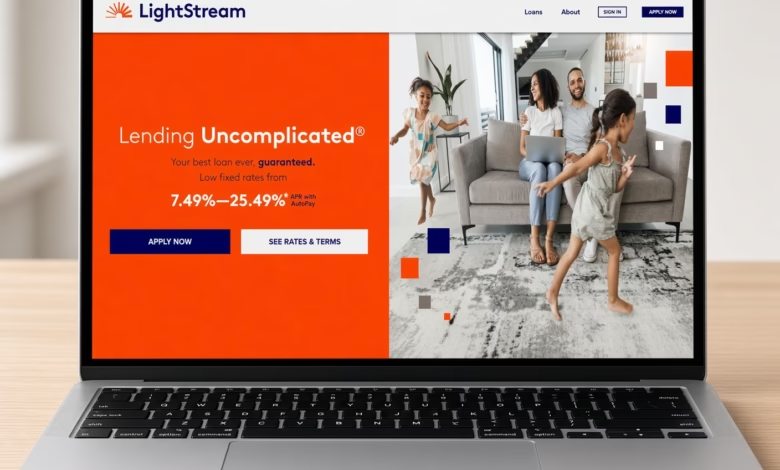
Navigating the vast ecosystem of modern personal finance can often feel overwhelming, especially when you are trying to fund a major life milestone, consolidate high-interest debt, or manage an unexpected financial expense. Among the numerous online lending options available today, LightStream has carved out a distinct reputation as a premier online lending division. Understanding how this alternative lending model works requires taking a closer look at its unique application mechanics, credit benchmarks, funding structures, and specialized financial products designed for consumers who exhibit strong fiscal responsibility.
What is LightStream Lending and How Does It Operate?
LightStream functions entirely as an online consumer lending platform. Rather than operating traditional brick-and-mortar storefronts where customers sit across a desk from a loan officer, the entire ecosystem is digitized. Borrowers interact with a streamlined web interface to request funds for practically any legitimate purpose.
As an unsecured lending product, meaning borrowers do not have to put up collateral like a house or a car to back the loan, the system relies heavily on the borrower’s overall creditworthiness, financial stability, and historical track record of managing debt. The operational framework is designed to eliminate friction, cutting out application fees, origination charges, and closing costs entirely. This fee-free structure changes how traditional lending costs are perceived, allowing every dollar borrowed to go directly toward the intended project or purchase.
Understanding the Core Eligibility Requirements
Because these unsecured loans often involve substantial amounts of capital, the qualifying criteria are structured to target individuals with good-to-excellent credit profiles. Meeting basic age and residency rules is only the starting point; the underwriting model dives much deeper into an applicant’s financial background.
When evaluating an application, the review engine examines several key pillars:
-
Extensive Credit History: The platform looks for a diverse mix of established credit accounts over several years, such as major credit cards, past auto loans, mortgages, or previous installment loans.
-
Sufficient Savings and Assets: Demonstrating an ability to save money through retirement accounts, investment portfolios, or liquid checking and savings balances strengthens an application.
-
Manageable Debt-to-Income Ratio: Applicants must prove a stable, reliable income that comfortably covers current monthly obligations alongside the new proposed loan payment.
-
Immaculate Payment History: A consistent history of paying past bills and credit obligations on time is heavily weighted during the evaluation process.
The Step-by-Step Online Application Process
The journey from submitting an initial request to seeing funds land in a bank account is designed to be completed in a matter of minutes. Because there is no preliminary soft-credit pre-qualification phase that shields credit scores, applicants typically prepare their financial details beforehand to ensure a smooth submission.
The standard procedure unfolds through a few distinct phases:
-
The Digital Submission: The borrower visits the secure online portal, selects the intended loan category, specifies the desired loan amount, and fills out personal, employment, and financial identification data.
-
Underwriting and Decision: During standard business hours, automated systems and human underwriters evaluate the complete financial profile. Responses are typically delivered rapidly.
-
Reviewing and Electronic Signing: Once approved, the applicant receives a detailed loan agreement outlining the fixed interest rate, monthly payment amounts, and chosen repayment timeline. Reviewing these disclosures carefully precedes signing the documents electronically.
-
Setting Up AutoPay and Funding Preferences: Borrowers provide their electronic banking details for fund disbursement and choose to enroll in automatic monthly payments to secure a lower interest rate discount. Completing these steps within designated morning windows can often trigger same-day funding into the borrower’s personal bank account.
Exploring Loan Amounts, Repayment Terms, and Fixed Rates
Flexibility is a primary hallmark of this lending model. Borrowers can request substantial capital ranging from five thousand dollars all the way up to one hundred thousand dollars. This wide spectrum accommodates everything from minor home updates to major luxury purchases or expansive debt consolidation strategies.
Repayment timelines are similarly flexible, often scaling from twenty-four months up to eighty-four months, or even longer depending on the specific loan category. All issued loans utilize a fixed-rate, simple-interest structure. This means the interest rate remains locked from the day the funds are disbursed until the final payment is made, protecting the borrower from unpredictable market fluctuations. Monthly installments are structured to fully amortize over the life of the loan, ensuring that each payment covers the accrued daily interest while chipping away at the remaining principal balance.
Versatile Loan Purposes: What Can the Funds Be Used For?
Unlike specialized financing options that restrict capital usage—such as a conventional auto loan that only purchases a car from a licensed dealership—unsecured personal financing offers incredible versatility. Borrowers maintain the freedom to direct funds toward almost any worthwhile personal or financial objective.
Common ways consumers utilize these funds include:
-
Home Improvement and Renovation: Upgrading kitchens, installing backyard swimming pools, landscaping, putting on new roofs, or adding solar panels to residential properties.
-
Debt Consolidation: Merging multiple high-interest credit card balances or retail accounts into a single, predictable monthly payment with a potentially lower fixed interest rate.
-
Major Recreational Purchases: Buying boats, RVs, jet skis, or classic collector cars through private party sales rather than dealing with restrictive dealer financing.
-
Life Events and Personal Expenses: Managing large medical bills, financing adoption fees, covering legal expenses, or paying for higher education costs.
Evaluating the Absence of Fees and Prepayment Penalties
A major factor influencing how economical these loans can be is the complete lack of hidden transactional costs. Traditional lending institutions frequently pad their profit margins with upfront origination fees, application processing charges, late payment penalties, or strict fees for paying off a balance ahead of schedule.
The operational model removes these barriers entirely:
-
Zero Origination Fees: Borrowers receive 100 percent of the requested loan proceeds without a percentage being skimmed off the top.
-
No Prepayment Penalties: Consumers are actively encouraged to become debt-free faster. Extra payments can be made at any time, or the entire remaining balance can be settled early without incurring any financial penalty. Simple interest calculations mean that paying down the principal early naturally reduces the total overall interest paid across the lifespan of the agreement.
Analyzing the Rate Beat Program and Competitive Pricing
To maintain a competitive edge in the broader financial marketplace, the platform utilizes unique pricing mechanisms designed to reward savvy consumers. One standout feature is the distinctive rate beat program. If a qualified applicant receives an approved loan offer with a lower interest rate from a competing institutional lender for the exact same terms, the platform provides an opportunity to submit that competing offer for review. When verified successfully, the service adjusts its terms to beat the competitor’s rate by a specified margin, ensuring the borrower secures highly advantageous pricing without needing to shop around endlessly.
Furthermore, interest rates are heavily optimized through automated payment enrollment. Setting up the monthly disbursement to pull automatically from a checking account grants a fractional percentage point discount on the overall annual percentage rate. Maintaining clean financial habits, high credit scores, and manageable debt levels remains the most reliable path toward unlocking the lowest advertised tiers.
Comparing the Pros and Drawbacks for Prospective Borrowers
Before committing to any financial product, weighing the distinct advantages against potential limitations helps clarify whether the option aligns with personal financial goals.
The Primary Advantages:
-
Access to unusually high borrowing limits, stretching up to one hundred thousand dollars for qualified individuals.
-
Extended repayment terms that provide flexibility in structuring comfortable monthly budgets.
-
Complete absence of application, origination, or early payoff penalty fees.
-
Rapid processing times that can put cash into a bank account on the very same business day.
The Potential Limitations:
-
A high minimum borrowing threshold of five thousand dollars, which may exceed what someone needs for smaller expenses.
-
Strict underwriting standards that require robust credit histories, making it difficult for younger or credit-building consumers to qualify.
-
The absence of a soft-check pre-qualification tool means submitting an application results in a hard inquiry on the credit report.
Making the Final Decision on Your Financial Strategy
Choosing how to finance a major purchase or streamline your liabilities is a decision that demands careful calculation of your current economic standing and future earning stability. By understanding the mechanical inner workings of specialized digital lending networks, borrowers can better prepare their financial portfolios to meet strict underwriting criteria. Whether you are planning a massive home renovation project, purchasing a recreational vehicle, or consolidating scattered debt, evaluating these streamlined digital platforms offers a clear roadmap toward achieving your long-term financial milestones with confidence and clarity.