How Do Insurance Companies Determine Your Premium?
Discover how insurers assess risk and determine the price you pay for an insurance policy
Navigating the world of insurance can sometimes feel like trying to solve a complex puzzle. You receive your monthly bill, look at the number, and wonder: How exactly did the insurance company arrive at this specific figure? Whether you are shopping for auto, home, life, or health insurance, understanding the mechanics behind premium calculations can empower you to make smarter financial choices, lower your costs, and secure the exact coverage you need without overpaying.
Insurance is fundamentally a business built on risk assessment and actuarial science. Behind every quote is a massive collection of data, statistical models, and risk-evaluation algorithms designed to predict the likelihood that you will file a claim. When you understand the underlying factors that influence these rates, you can take proactive steps to present yourself as a low-risk policyholder.
The Core Philosophy of Insurance: Risk Pooling and Actuarial Science
To understand how insurance companies determine your premium, you must first understand the fundamental concept of insurance itself: risk pooling. An insurance company does not insure just one person; instead, it collects premiums from thousands or millions of policyholders into a massive financial pool. When an unfortunate event happens to one person—such as a car accident, a house fire, or a medical emergency—the insurer pays out the claim using the funds gathered from that collective pool.
Because the insurer must ensure there is always enough money in the pool to cover potential disasters while still making a sustainable profit, they cannot charge everyone the same flat rate. Charging a cautious driver with a clean record the same amount as a reckless driver with multiple speeding tickets would be economically unsustainable. Instead, insurers rely heavily on actuaries—statistical experts who use mathematical models, historical data, and probability theories to analyze risk and establish pricing structures.
Actuaries look at vast historical datasets to identify trends and correlations. They ask questions like: Which demographic groups get into the most accidents? Which neighborhoods experience the highest rates of property theft? What underlying health conditions correlate with longer hospital stays? By answering these questions through empirical data, insurers can assign a precise risk score to every individual applicant.
Key Factors That Influence Auto Insurance Premiums
Auto insurance is one of the most common types of coverage purchased by consumers, and it serves as a primary example of how personal variables dramatically shift your pricing. When an auto insurer evaluates your application, they examine a multi-layered profile.
Driving Record and History
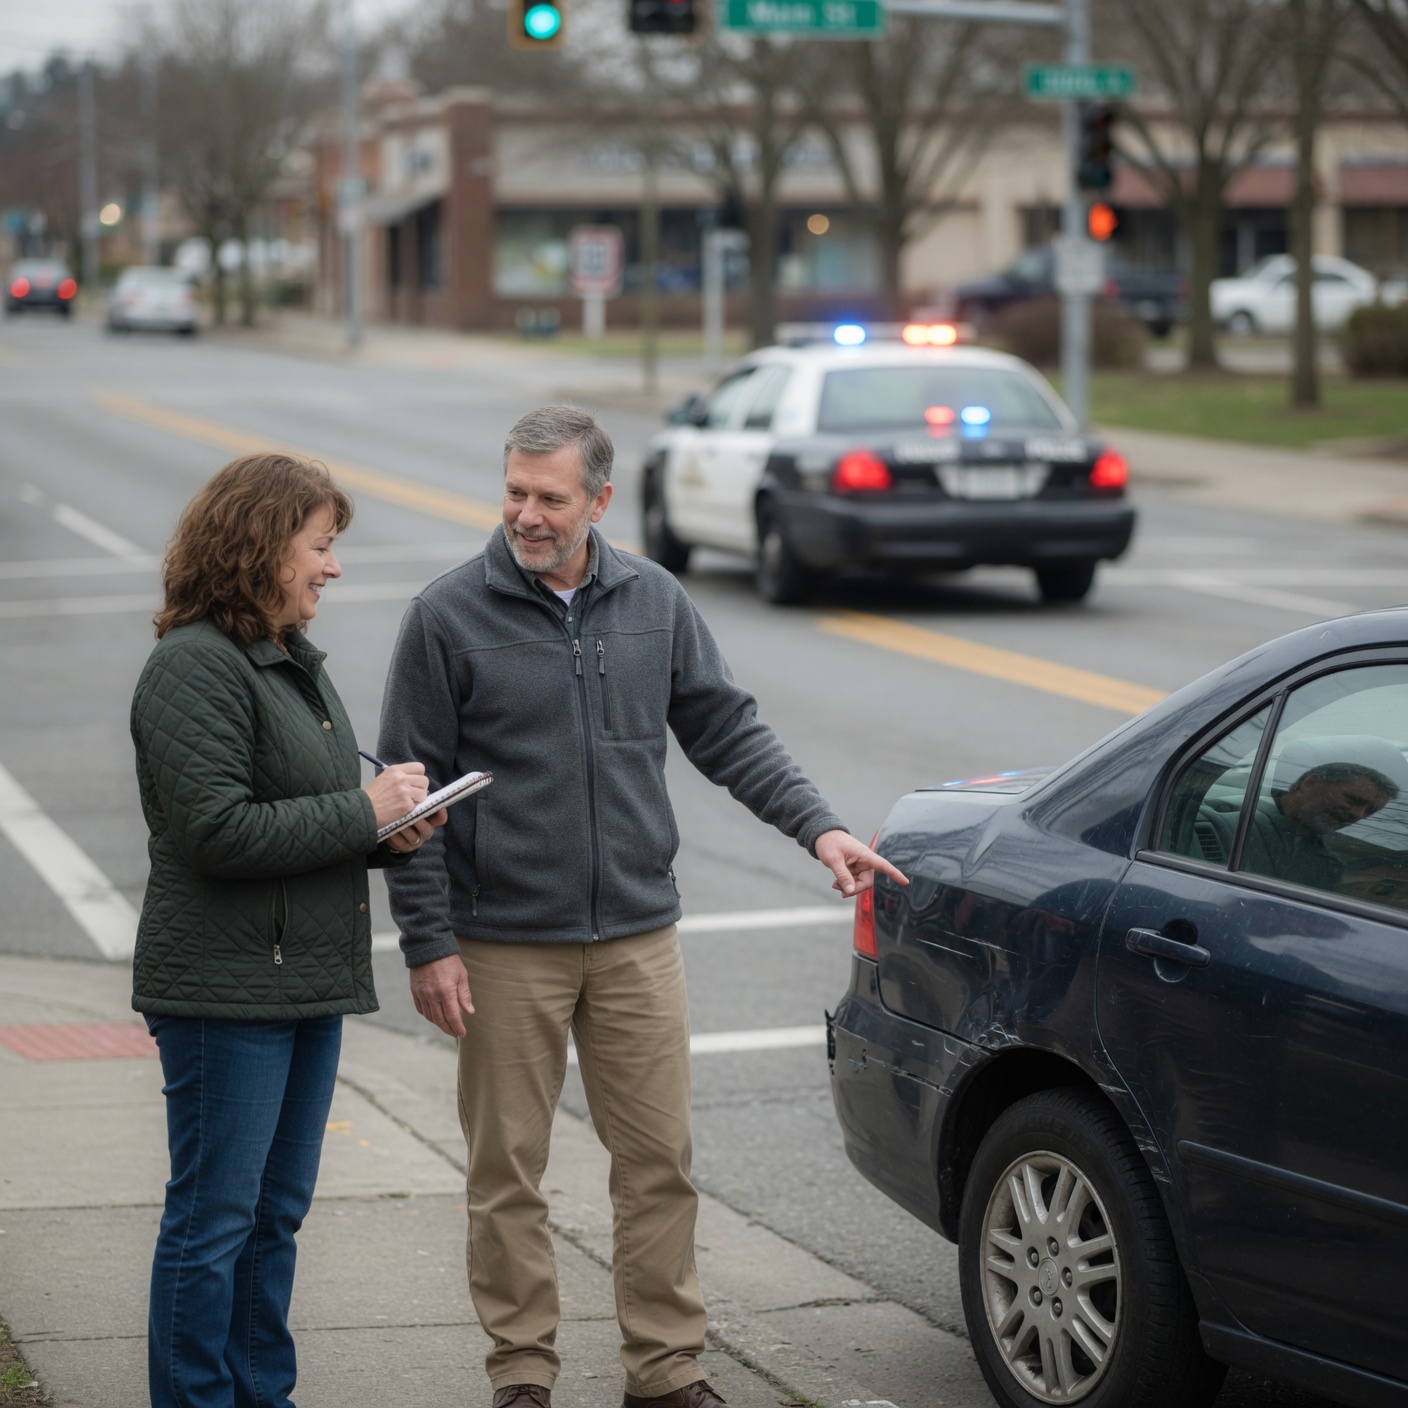
Your driving history is perhaps the single most significant factor in determining your car insurance premium. Insurers review your Motor Vehicle Record (MVR) for the past three to five years, searching for moving violations, speeding tickets, reckless driving charges, and at-fault accidents. A clean driving record indicates caution and responsibility, resulting in lower rates. Conversely, multiple infractions signal a high probability of future claims, triggering substantial premium hikes.
Vehicle Make, Model, and Safety Features
The type of car you drive matters immensely. Insurance companies analyze historical repair costs, safety ratings, theft rates, and engine sizes for every vehicle make and model. A luxury sports car with expensive aluminum body panels and high horsepower will cost significantly more to insure than a modest, highly-rated family sedan equipped with modern advanced driver-assistance systems (ADAS) such as automatic emergency braking and lane-keep assist.
Location and Garaging Zip Code
Where you live and where your car spends its nights heavily impacts your bill. Urban areas typically feature higher rates due to heavier traffic congestion, increased risk of collisions, higher rates of vehicle vandalism, and higher costs for local auto body repairs. Furthermore, if your zip code experiences frequent severe weather events—such as hail storms, hurricanes, or floods—your comprehensive insurance pricing will reflect those environmental risks.
Annual Mileage and Commute Distance
The more time you spend behind the wheel, the higher your mathematical exposure to potential accidents. Insurers will ask about your daily commute distance and your estimated annual mileage. Individuals who work from home or use public transportation will generally pay much lower premiums than long-distance commuters who navigate heavy rush-hour traffic every single day.
Driver Demographics: Age, Gender, and Marital Status
While frustrating to some consumers, statistical data consistently shows clear behavioral trends across demographic lines. Teenagers and young adults under the age of 25 statistically lack driving experience and exhibit higher rates of reckless driving; consequently, they face the highest insurance premiums in the industry. As drivers age into their thirties and forties, rates tend to stabilize and decrease, provided their driving record remains clean. Statistical analyses also show that married individuals historically file fewer claims than single drivers, which can sometimes result in modest rate adjustments.
Key Factors That Influence Homeowners Insurance Premiums
Purchasing a home is one of the largest financial investments you will ever make, and protecting it requires a homeowners insurance policy. Much like auto insurance, home insurance pricing relies on a meticulous evaluation of physical and environmental risk elements.
Replacement Cost vs. Market Value
A common misconception is that home insurance premiums are based on the real estate market value of your house. In reality, insurers calculate rates based on the structural replacement cost—the actual cost of labor and materials required to rebuild your home from the ground up using similar quality construction in the event of a total loss. Local construction costs, square footage, architectural complexity, and building materials all directly impact this calculation.
Age and Condition of the Home’s Systems
The structural integrity of a property dictates its risk profile. Older homes with aging electrical wiring, outdated plumbing systems, and deteriorating roofs present a much higher hazard for fire, water damage, and structural failure. Insurers frequently request inspections or details regarding when the roof, HVAC systems, and water heater were last updated. Modern construction featuring updated systems commands significantly better rates.
Claims History of the Property and Owner
Insurance companies utilize shared industry databases (such as C.L.U.E. reports) to track historical insurance claims associated with both the property and the individual applicant. If a home has experienced multiple water damage or weather-related claims over the past few years, insurers view it as a high-risk property. Similarly, if you have a history of filing frequent claims on previous properties, your overall risk score increases.
Proximity to Emergency Services and Protective Devices
How quickly can local firefighters respond to an emergency at your address? Insurers evaluate your distance from the nearest fire hydrant and fire station. Additionally, homes equipped with advanced risk-mitigation features—such as monitored security systems, smoke detectors, deadbolt locks, automatic water shut-off valves, and storm shutters—often qualify for attractive policy discounts.
Key Factors That Influence Life and Health Insurance Premiums

When transitioning to personal lines of coverage such as life or health insurance, the evaluation shifts heavily away from external assets and focuses deeply on your personal biological and lifestyle profile.
Age and Life Expectancy
Age is the primary driver of life and health insurance premiums. As human beings age, natural biological mortality rates increase. Buying a term life insurance policy in your twenties or thirties locks in exponentially lower rates compared to purchasing the exact same coverage in your fifties or sixties, simply because the statistical probability of payout is lower over the term duration.
Medical History and Family Health Background
Underwriters analyze your personal medical history, including past surgeries, chronic illnesses, and ongoing prescription medications. They also evaluate your immediate family medical history—specifically looking at hereditary conditions such as heart disease, diabetes, or certain types of cancer that may impact your long-term longevity.
Lifestyle Habits: Tobacco Use and Dangerous Hobbies
Lifestyle choices carry immense weight in premium calculations. Tobacco use—whether cigarettes, cigars, or vaping products—drastically increases the risk of numerous medical complications, resulting in tobacco users paying up to double or triple the rates of non-smokers. Furthermore, engaging in high-risk recreational hobbies like skydiving, rock climbing, scuba diving, or private aviation will result in specialized underwriting and potential premium surcharges.
The Role of Credit Scores in Insurance Pricing
In many regions and for many types of property and casualty insurance, companies utilize a specialized metric known as an insurance credit score or credit-based insurance score. This is distinct from the traditional FICO score used by mortgage lenders, though it is derived from similar credit report data.
Statistical studies conducted across the insurance industry over decades have demonstrated a strong correlation between how individuals manage their financial obligations and how likely they are to file insurance claims. Policyholders with strong credit scores statistically exhibit higher financial responsibility, pay bills on time, and manage risk carefully, resulting in fewer claims. Conversely, poor credit histories are statistically correlated with higher claim frequencies. While some states have restricted or banned the use of credit scores in insurance underwriting, it remains a dominant pricing factor in many major markets.
Deductibles, Coverage Limits, and Policy Structure
Beyond your personal background and risk profile, the structural configuration of the insurance policy itself plays a massive role in determining your ultimate premium price tag.
Understanding Deductibles
A deductible is the predetermined out-of-pocket amount you agree to pay toward a loss before your insurance coverage kicks in to cover the remainder. There is an inverse relationship between deductibles and premiums: the higher your deductible, the lower your monthly or annual premium. For example, opting for a 1,000-dollar deductible instead of a 500-dollar deductible shifts more short-term financial risk onto you, rewarding you with cheaper ongoing rates.
Coverage Limits and Endorsements
The maximum amount your insurer will pay for a covered loss is your coverage limit. Selecting higher coverage limits or purchasing optional policy endorsements (such as umbrella liability policies, roadside assistance, or jewelry riders) increases the insurer’s financial exposure. Naturally, comprehensive, high-limit coverage costs more than bare-minimum state-mandated coverage.
Practical Strategies to Lower Your Insurance Premiums
Knowing how insurers calculate rates gives you the tactical advantage needed to actively reduce your expenses. Here are several proven strategies to optimize your insurance costs:
- Bundle Your Policies: Most insurance carriers offer substantial multi-policy discounts if you purchase your auto, homeowners, and renters insurance through the exact same company.
- Maintain Good Credit: Routinely monitor your credit report, pay down outstanding debts, and pay your bills on time to maintain a strong insurance credit score.
- Shop Around and Compare Quotes: Insurance pricing models vary wildly between different carriers. Getting quotes from multiple competing companies every few years ensures you secure the best rate.
- Utilize Telematics and Safe Driving Programs: Many auto insurers offer smartphone apps or plug-in tracking devices that monitor your actual driving habits—such as speed, braking smoothness, and phone usage—rewarding safe drivers with deep discounts.
- Increase Your Deductibles Wisely: If you maintain a healthy emergency savings fund, raising your deductibles can immediately slash your regular premium payments.
- Ask About Available Discounts: Inquire about lesser-known discounts, such as paperless billing, automatic payment sign-ups, defensive driving course completions, and safety equipment credits.

Insurance premium calculation is far from a random guessing game. It is a sophisticated, data-driven science designed to evaluate risk, project future probabilities, and maintain financial stability across massive risk pools. By understanding the intricate combination of driving records, property characteristics, biological health profiles, and policy structures that underwriters examine, you gain the clarity needed to take control of your financial security. Armed with this knowledge, you can adopt habits that lower your risk profile, adjust your policy settings strategically, and shop the market effectively to secure the robust protection you deserve at a price that fits your budget.