How Does an Insurance Policy Work?
Learn how an insurance policy works, including coverage, premiums, deductibles, exclusions, and claims
Insurance is one of those financial tools that most of us purchase because we have to—whether mandated by law for our vehicles, required by lenders for our homes, or chosen voluntarily for peace of mind regarding our health and family. Yet, despite paying premiums month after month, many policyholders never truly dive into the mechanics of how an insurance policy actually works until they are faced with an unexpected emergency or a major loss.
Understanding the architecture of an insurance policy is essential not just for financial literacy, but for ensuring you are properly protected when life throws an unexpected curveball. From the foundational concept of risk pooling to the fine print of deductibles, exclusions, and claim settlements, this guide breaks down everything you need to know about how insurance operates in the United States.
The Fundamental Concept: How Risk Pooling and the Law of Large Numbers Drive Insurance
At its core, insurance is a mechanism of risk management. It is designed to transfer the financial burden of a potentially devastating loss from an individual to a large collective group. To understand how this works, we must look at two foundational economic principles: the Law of Large Numbers and Risk Pooling.
The Law of Large Numbers is a statistical theory which states that as the number of trials or observations increases, the actual results will get closer to the expected probability. In the insurance industry, this means that while it is impossible to predict exactly which individual driver will get into a car accident next Tuesday, actuaries can accurately predict how many accidents will occur out of a pool of one million drivers in a specific region over the course of a year.
Through Risk Pooling, insurance companies gather thousands or millions of policyholders who face similar risks. Every member pays a smaller, manageable amount of money—known as a premium—into a central fund. When a member of that pool experiences a covered loss, the insurance company compensates them out of that shared pool of money. Thus, the collective contributions of the many cover the catastrophic losses of the few.
The Anatomy of an Insurance Contract: Key Components Every Policyholder Must Know
An insurance policy is a legally binding contract between you (the insured) and the insurance company (the insurer). Like any legal contract, its language can be dense and intimidating. However, nearly every standard property, casualty, life, or health insurance policy in the United States is constructed using a standard structural framework:
- Declarations Page (Dec Page): Usually located at the very front of your policy documents, this is the summary sheet. It outlines who is insured, the specific property or life being covered, the policy period (start and end dates), the limits of coverage, and the exact premium you are obligated to pay.
- Insuring Agreements: This is the core promise made by the insurance company. It details what the insurer agrees to do, the specific perils (causes of loss) they will cover, and under what general conditions they will provide financial compensation.
- Exclusions: Exclusions explicitly state what the policy does not cover. Common exclusions help insurance companies manage catastrophic, systemic risks that cannot be pooled affordably—such as war, intentional acts of destruction, or specific natural disasters like earthquakes or floods, which often require separate standalone policies.
- Conditions: These are the rules and responsibilities that both the policyholder and the insurer must follow. For example, a standard condition of an auto insurance policy is that you must report an accident to the police and the insurer within a reasonable timeframe. Failure to adhere to these conditions can result in a denied claim.
- Endorsements and Riders: These are amendments, add-ons, or modifications to the base policy. They allow you to customize your coverage by either adding protection for specific high-value items (like jewelry or specialized computer equipment) or removing certain standard provisions.
Financial Mechanics: Premiums, Deductibles, and Copays Explained
Navigating the cost of insurance requires a firm grasp of several key financial terms. Your out-of-pocket expenses and recurring costs are governed by how these variables interact with one another:
The Premium: This is the price you pay—monthly, quarterly, or annually—to keep your insurance policy active. Insurance companies calculate your premium based on risk assessment. An underwriter evaluates your historical data, credit score, geographic location, lifestyle habits, and claim history to assign a risk score. Higher risk generally translates to a higher premium.
The Deductible: A deductible is the specific amount of money you agree to pay out of pocket before your insurance coverage kicks in and begins paying for a loss. For example, if your home suffers 10,000 dollars in storm damage and your policy has a 1,000 dollar deductible, you will pay the first 1,000 dollars, and your insurance company will cover the remaining 9,000 dollars up to your policy limits.
There is a direct economic trade-off between premiums and deductibles:
- High Deductible, Low Premium: Choosing a higher deductible lowers your monthly insurance bill because you are accepting more financial responsibility if an incident occurs.
- Low Deductible, High Premium: Choosing a lower deductible increases your monthly premium because the insurance company assumes more financial risk right from the start of a claim.
Copays and Coinsurance: Primarily found in health and medical insurance, a copay is a fixed dollar amount you pay for a specific medical service (such as 30 dollars for a doctor’s visit), while coinsurance is the percentage of medical costs you pay after meeting your deductible (such as paying 20 percent of a hospital bill while the insurer pays 80 percent).
The Lifecycle of an Insurance Policy: From Application to Renewal
An insurance policy is not a static document; it goes through a distinct lifecycle that requires active management by both the consumer and the provider. Understanding each stage helps ensure uninterrupted coverage and optimal pricing.
1. Underwriting and Application: The process begins when you apply for coverage. You provide personal information, and the insurer evaluates your risk profile. Based on actuarial tables and underwriting guidelines, the company decides whether to accept your application, what exclusions to apply, and how much to charge for your premium.
2. Policy Activation and Payment: Once your application is approved and your initial premium payment is processed, the policy becomes active on its effective date. You enter the policy term—which is typically six months to one year for auto and home insurance, or renewed monthly for health policies.
3. Policy Maintenance and Adjustments: Throughout the policy term, your life circumstances may change. You might buy a new car, renovate your kitchen, get married, or move to a different state. It is vital to notify your insurer of these life events because they can directly impact your risk profile and ensure your coverage limits remain adequate.
4. Renewal or Cancellation: As your policy term approaches its expiration date, the insurance company evaluates your claims history over the past year. If you have maintained a clean record, your policy will typically renew automatically, though premium rates may adjust based on broader economic inflation and regional risk trends. If you experience multiple claims or major risk changes, the insurer may issue a non-renewal notice.
How the Claims Process Works Step-by-Step
The true test of any insurance policy occurs when you need to file a claim. While the claims process can vary slightly depending on whether you are dealing with auto, home, or health insurance, the fundamental steps remain consistent:
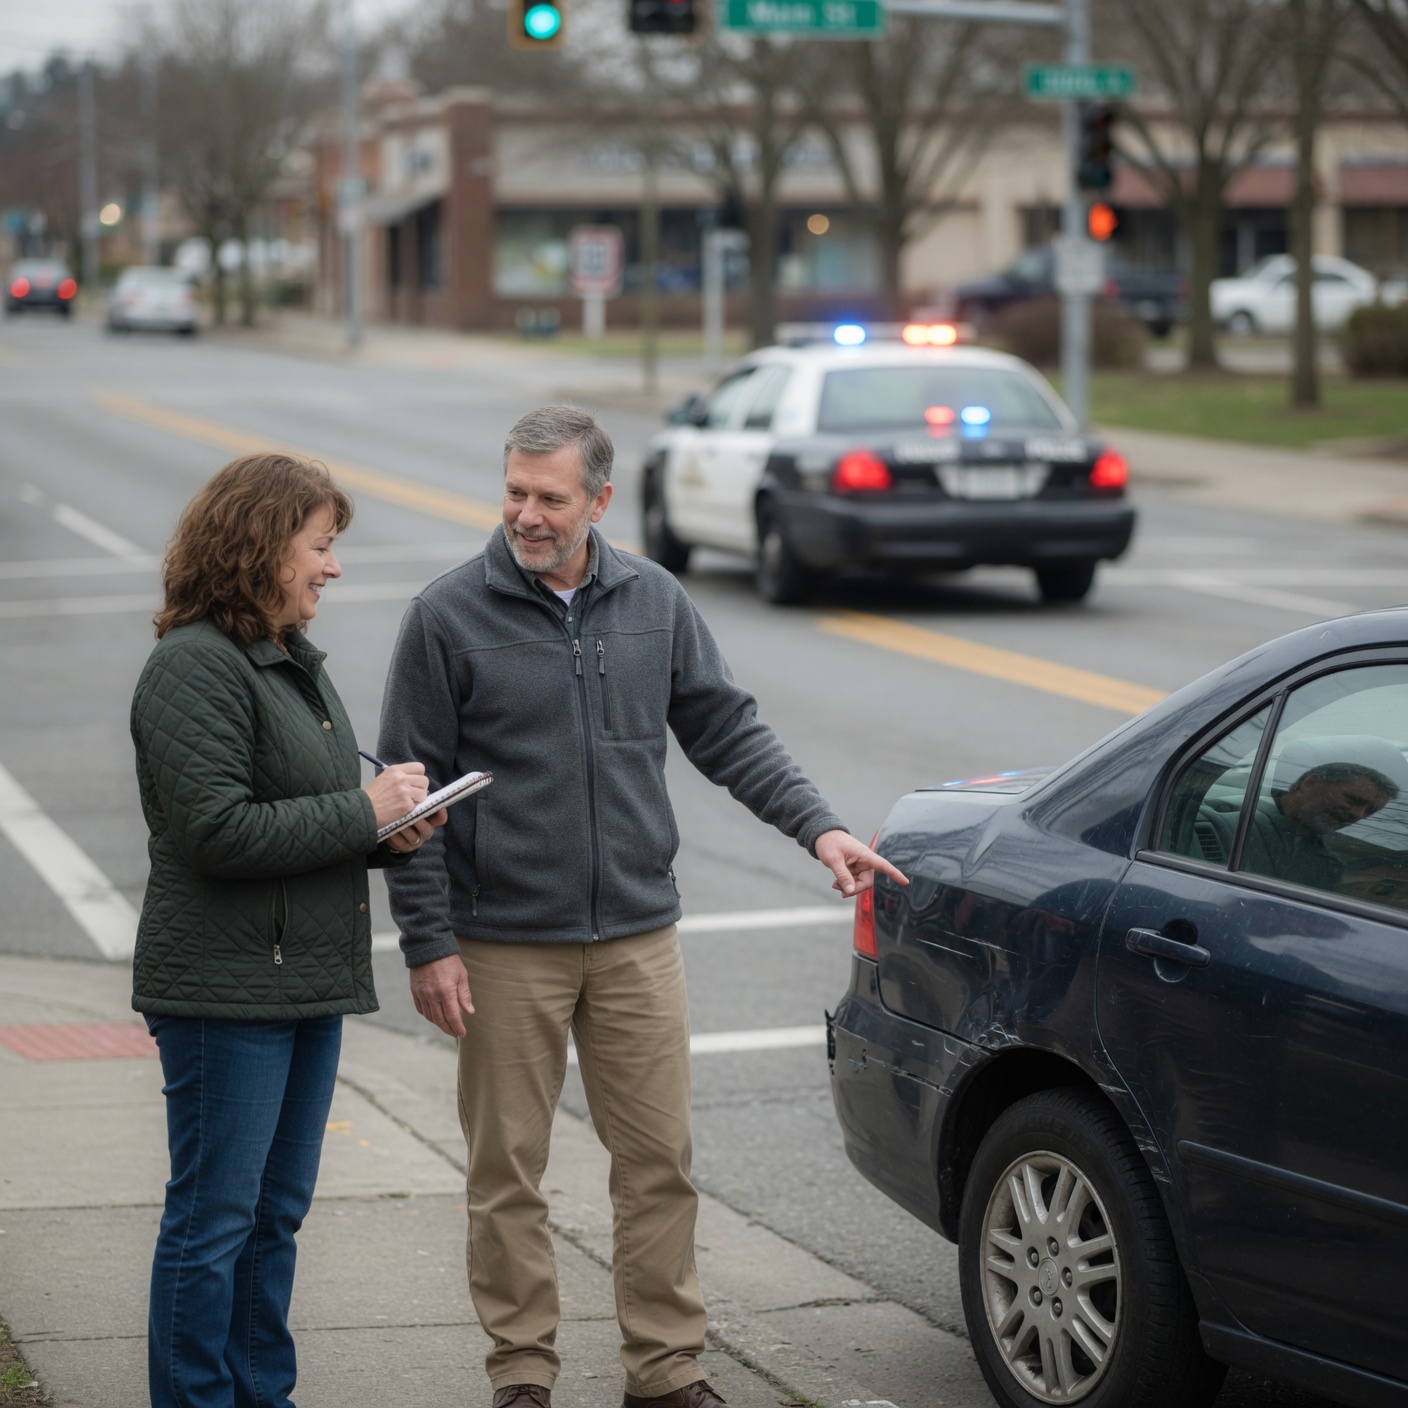
- Step 1: Immediate Notification: Following an incident—such as a fender bender, a kitchen fire, or a medical emergency—you must contact your insurance company as soon as reasonably possible. Delaying notification can sometimes jeopardize your right to compensation under the terms of your contract.
- Step 2: Documentation and Evidence: Gather as much objective evidence as possible. Take photographs and videos of property damage, obtain police reports for accidents or thefts, keep detailed medical records and receipts, and write down a chronological timeline of events while your memory is fresh.
- Step 3: Claims Investigation and Adjuster Assignment: Once a claim is filed, the insurance company assigns an adjuster. The adjuster is a specialized investigator whose job is to inspect the damage, review your policy contract, interview witnesses, and determine the extent of the insurer’s financial liability.
- Step 4: Settlement and Payout: After the investigation concludes, the insurer calculates the payout based on your policy limits, actual cash value (ACV) versus replacement cost, and your deductible. If approved, funds are disbursed so you can repair your property, replace lost items, or pay medical bills.
Understanding Actual Cash Value (ACV) Versus Replacement Cost Value (RCV)
One of the most critical distinctions in property and casualty insurance is how your belongings or structures are valued when a claim is processed. Grasping this difference prevents unpleasant financial surprises after a disaster.
Actual Cash Value (ACV): ACV calculates the current market value of an item by taking its original purchase price and subtracting depreciation due to age, wear, and tear. For example, if your five-year-old television is destroyed in a fire, an ACV policy will only pay out what that specific five-year-old television was worth on the open market immediately before the fire—not what it costs to buy a brand-new equivalent today.
Replacement Cost Value (RCV): RCV policies pay out the amount of money required to purchase a brand-new item of like kind and quality at current market prices, without any deduction for depreciation. While RCV policies offer significantly superior protection, they also command higher premiums because the insurance company takes on a much higher payout liability.
Different Types of Insurance and Their Unique Operational Mechanics
While the general philosophy of risk pooling applies across the board, different branches of insurance operate with distinct rules, legal frameworks, and objectives:
Auto Insurance: Mandatory in nearly every U.S. state, auto insurance combines liability coverage (which pays for injuries and property damage you cause to other drivers) with physical damage coverage (collision and comprehensive insurance for your own vehicle). Its mechanics heavily weigh driving records, vehicle safety ratings, and annual mileage.
Homeowners Insurance: Designed to protect your physical dwelling and personal possessions against a wide array of perils, it also includes personal liability protection if a visitor is injured on your property. Mortgage lenders require proof of homeowners insurance before issuing loans.
Health Insurance: Operates through complex networks of doctors, hospitals, and pharmaceutical providers. It manages medical expenses through negotiated provider discounts, deductibles, copays, and annual out-of-pocket maximum limits designed to prevent medical bankruptcy.
Life Insurance: Unlike property or health insurance which covers operational events, life insurance is designed to provide financial security to your designated beneficiaries after your death. Term life insurance provides coverage for a specific number of years with pure protection, while permanent life insurance (such as whole or universal life) combines a death benefit with an investment or cash-value accumulation component.
Smart Strategies to Optimize Your Insurance Coverage and Manage Costs
Because insurance is a recurring fixed expense that can strain household budgets, consumers should regularly review their portfolios to ensure they are getting maximum value without sacrificing essential protection. Consider these practical strategies:
- Bundle Your Policies: Most major insurance providers offer substantial multi-policy discounts if you purchase your auto, home, and umbrella insurance through the same company. Bundling simplifies your financial management and lowers overall premiums.
- Maintain a Strong Credit Score: In most U.S. states, insurance companies use credit-based insurance scores to help determine premium rates. Statistics show a strong statistical correlation between responsible credit management and lower insurance claim frequencies.
- Increase Deductibles Wisely: If you maintain a healthy emergency savings fund, opting for a higher deductible can drastically reduce your monthly premiums over time, saving you money in years where you file no claims.
- Review and Update Coverage Annually: Life changes rapidly. Ensure your policy limits reflect the current replacement cost of your home and possessions, and remove unnecessary coverages for assets you no longer own.
The True Value of a Well-Structured Insurance Policy
An insurance policy is far more than just a mandatory monthly bill or a legal checkbox; it is a vital pillar of personal financial security. By spreading risk across a massive pool of participants, insurance provides individuals and families with a financial safety net capable of withstanding life’s most unpredictable storms.
By understanding how insurance policies are constructed—from the foundational rules of premiums and deductibles to the nuances of exclusions, claims, and valuation methods—you empower yourself to make informed decisions. Taking the time to review your coverage choices today ensures that when the unexpected happens tomorrow, you and your assets remain fully protected.